Limited Time 100% Discount on Application fee. 

Dubai recorded AED 252 billion in real estate transactions during the first quarter of 2026, representing a 31% year-on-year increase, according to the Dubai Land Department. For buyers entering this active property market, establishing their financing eligibility before shortlisting properties is an important first step.
Mortgage pre-approval helps determine how much a bank may be willing to lend, what deposit you'll need and whether your financial profile meets the lender's requirements.
If you're looking to understand how to get pre-approved for a mortgage in the UAE, this guide explains the eligibility criteria, documents, application process and costs involved, including the issues that can affect approval.
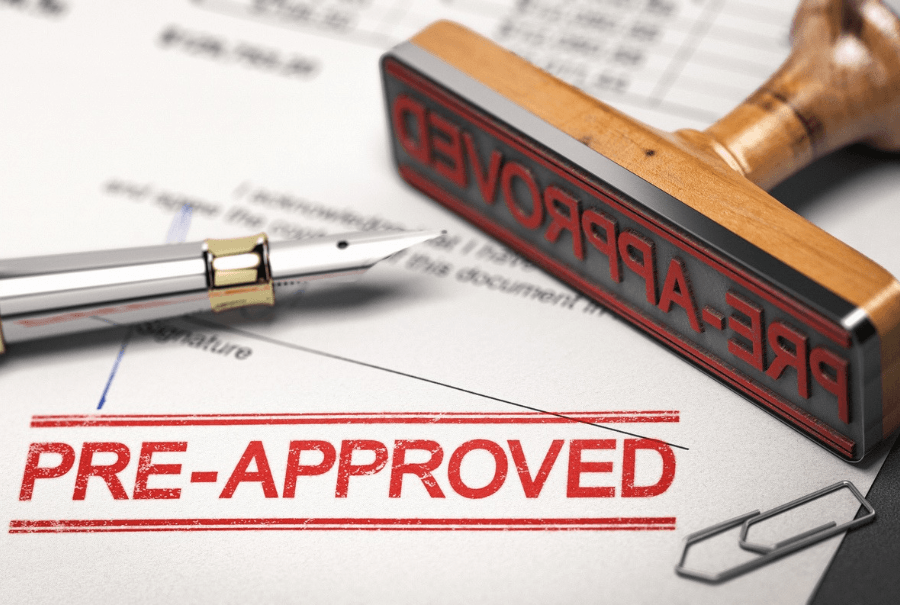
Mortgage pre-approval, also called Approval in Principle (AIP), is a conditional assessment of your borrowing eligibility.
A lender examines your income, employment or business history, credit report and existing financial commitments to determine an indicative loan amount.
Pre-approval is different from final mortgage approval. At this stage, the bank has primarily assessed your financial circumstances. Once you select a property, it must also verify the property's eligibility, arrange a valuation and complete its final underwriting and legal checks.
The amount stated in your pre-approval letter is therefore indicative, not guaranteed. Final financing remains subject to the lender's conditions and applicable mortgage regulations.
Obtaining pre-approval before searching for property offers several advantages:
Identify potential problems early: Address documentation gaps, credit exposure or affordability concerns before entering into a purchase agreement.
UAE mortgage eligibility varies by lender, mortgage product and applicant profile.
Banks generally consider:
The UAE Central Bank's mortgage framework sets maximum debt-burden ratios of 50% for expatriates and 60% for UAE nationals. Banks may impose stricter affordability criteria. (Source: UAE Central Bank Financial Stability Report)
Yes, depending on the lender's assessment method.
Some banks calculate a monthly liability equivalent to 5% of an applicant's credit card limit, even when the outstanding balance is zero.
For example, an unused credit card with an AED 60,000 limit could be assessed as an AED 3,000 monthly commitment.
This illustrative calculation is supported by the Al Ahli Bank of Kuwait mortgage key facts statement. Other lenders may use different methods.
Review your credit facilities and outstanding liabilities before applying. Closing a credit card does not automatically improve eligibility, so seek advice before making changes.
Lenders require documents to verify identity, income, financial stability and existing obligations.
The following checklist covers common requirements.
| Salaried applicants | Self-employed applicants | Non-resident applicants |
| Passport and Emirates ID | Passport and Emirates ID, where applicable | Valid passport |
| UAE residence visa, where applicable | UAE residence visa, where applicable | Proof of overseas residential address |
| Salary certificate | Valid trade licence | Employment and income confirmation |
| Typically 3–6 months of bank statements | Typically 6–12 months of personal and business statements | Home-country bank statements |
| Payslips, where required | Audited financial statements, where required | Overseas credit report, where required |
| Existing loan details and AECB consent | MOA or partnership deed, where applicable, and AECB consent | Existing liability details |
These are indicative document requirements. Statement periods, credit checks and additional records vary by lender and mortgage product.
The mortgage pre-approval process in the UAE generally follows these steps.
Begin by reviewing your monthly income, outstanding loans, credit card facilities and credit history.
Your debt-burden ratio helps determine how much of your income is available for mortgage repayments.
A mortgage adviser such as BNW can assess your financial profile against lender requirements before an application is submitted.
Your borrowing eligibility and property budget are not necessarily the same.
Under UAE Central Bank regulations, eligible expatriates purchasing their first owner-occupied property valued at AED 5 million or below can generally borrow up to 80% of its value. The corresponding maximum for eligible UAE nationals is 85%.
Different limits apply to other property categories.
For an eligible AED 2 million property purchase with 80% financing:
| Particulars | Amount |
| Purchase price | AED 2,000,000 |
| Mortgage financing | AED 1,600,000 |
| Buyer down payment | AED 400,000 |
Additional purchase and financing charges must be budgeted separately.
Mortgage products differ in pricing, repayment structures and associated fees.
A fixed-rate mortgage generally offers predictable repayments during the agreed fixed period. Variable-rate mortgages may fluctuate with a benchmark such as EIBOR, the Emirates Interbank Offered Rate.
Some products begin with a promotional fixed rate before switching to variable pricing.
Compare the applicable interest rate or profit structure, total borrowing cost, processing charges, valuation fees, insurance or takaful requirements and early settlement conditions.
Islamic home finance products may use different contractual arrangements, so review their payment and ownership terms carefully.
Gather the mortgage pre-approval documents required for your employment and residency category.
Your chosen bank or mortgage adviser will submit the application for assessment.
The lender may request additional statements, clarification of large deposits, proof of business income or information about existing loans.
Responding promptly and providing consistent records can help prevent avoidable delays.
Once the lender completes its preliminary assessment, it may issue a conditional pre-approval letter.
Before proceeding, check:
Clarify anything you do not understand before making a financial commitment.
Some lenders provide initial pre-approval without a separate fee, while others may charge an application or processing fee.
Buyers should also account for costs arising during the property purchase and final mortgage process.
| Expense | Indicative charge |
| Initial mortgage pre-approval | May be free; lender-dependent |
| Dubai property sale registration | 4% of the sale value |
| Dubai mortgage registration | 0.25% of the mortgage amount |
| Registration trustee service | AED 4,000 plus VAT for qualifying transactions of AED 500,000 or more |
| Bank processing and valuation | Varies by lender |
| Insurance or takaful | Varies by product and coverage |
The Dubai Land Department publishes its property sale registration and mortgage registration fees.
These are not all pre-approval charges. Most arise later in the transaction, and additional administrative, brokerage or developer charges may apply.
Request a complete cost estimate before committing to a purchase.
Ideally, apply before making an offer or signing a property purchase agreement.
This gives you time to understand your borrowing eligibility, arrange your down payment and address any financial issues.
However, pre-approvals have limited validity. Coordinate your application with your expected property search timeline to avoid unnecessary reassessments.
Once you've selected a property, the lender begins the final approval process.
This generally involves an independent property valuation, verification of ownership and legal documents, confirmation of property eligibility and final financial underwriting.
A valuation shortfall can affect the financing available.
For example, if you agree to purchase a property for AED 2 million but the bank values it at AED 1.9 million, financing at 80% of the valuation would provide AED 1.52 million.
You would need AED 480,000 towards the purchase price, excluding additional expenses. This assumes the lender permits the stated financing percentage and calculates the loan against the lower valuation.
Once the lender completes its checks, it can issue the final mortgage offer. The buyer must then satisfy the offer conditions, complete the required documentation and arrange payment of applicable charges before mortgage disbursement and property transfer.
Mortgage pre-approval is easier to navigate when you understand which lenders are likely to accept your financial profile, what documents they require and how their financing terms differ.
At BNW Mortgages, our team of over 25 mortgage advisers brings more than 19 years of experience to the UAE mortgage market. We work with major UAE banks such as Emirated NBD, Mashreq, Standard Chartered and more, to help buyers assess their eligibility, compare suitable mortgage products and manage the application process.
Our support extends beyond pre-approval. From documentation and bank coordination to final mortgage disbursement and property handover, we assist buyers throughout their financing journey.
Whether you're a UAE resident, non-resident investor or self-employed applicant, our advisers can help you understand the options available for your circumstances.
Ready to understand your borrowing capacity? Speak to BNW Mortgages to begin your mortgage pre-approval assessment.
How long does mortgage pre-approval take in the UAE?
Pre-approval typically takes up to five business days for UAE residents and up to 15 business days for non-resident or self-employed applicants.
Processing times depend on the lender, the completeness of your documents and whether additional financial verification is required. Some straightforward applications may be assessed sooner.
What do mortgage lenders need for pre-approval?
Lenders generally require proof of identity, income documentation, bank statements, credit information and details of existing liabilities.
Self-employed and non-resident applicants may need additional business, income or overseas financial records.
Can a mortgage be denied after pre-approval?
Yes. A lender may decline or reduce financing if the applicant's financial position changes, additional credit obligations arise, the property fails eligibility checks or the valuation does not support the requested loan.
Pre-approval does not guarantee final mortgage approval.
How long is mortgage pre-approval valid in the UAE?
Validity depends on the lender. HSBC UAE, for example, states that its Approval in Principle is valid for 60 calendar days. (Source: HSBC UAE)

